REITs in India are no longer a specialist secret: office towers are staying full, distributions are rising, and a new generation of Indian investors is quietly building real estate income without buying a single brick.
How REITs in India actually work
A Real Estate Investment Trust is a SEBI-regulated trust that owns and operates income-generating commercial real estate. REITs pool capital from investors to acquire large properties, typically office parks, retail malls, or warehouses, that would be inaccessible to individual investors directly.
SEBI mandates that REITs distribute at least 90% of their net distributable cash flows to unitholders. This distribution is not optional: it is a condition of the REIT structure. So investors receive income regularly, simply by holding units on a stock exchange.
A minimum of 80% of the value of a REIT’s assets must be invested in completed rent or income-generating properties. This rule keeps the portfolio productive and limits speculative exposure. India now has 5 listed REITs on NSE and BSE, minimum investment has been reduced to a single unit, and the RBI’s rate-cutting cycle has driven REIT unit prices up significantly while distribution yields remain attractive relative to other income instruments.
What REITs in India actually pay
REIT returns come from 2 sources: dividend income and capital appreciation. Both matter, but the income side is what draws most investors to this asset class in the first place.
Annualized yields in India are around 6 to 7%, influenced by occupancy rates, lease terms, and property management. As the underlying properties increase in value, the REIT units grow correspondingly. Average annualized total returns can reach 10 to 12% in favorable markets.
REITs in India distributed about Rs 1,559 crore to 2.7 lakh unitholders in the first quarter of 2025-26, which was 13% higher than the same quarter the previous year. The number of unitholders rose from 2.45 lakh to 2.7 lakh, confirming their growing popularity. That growth in the unitholder base is the clearest signal that ordinary investors are paying attention.
Where the office market stands
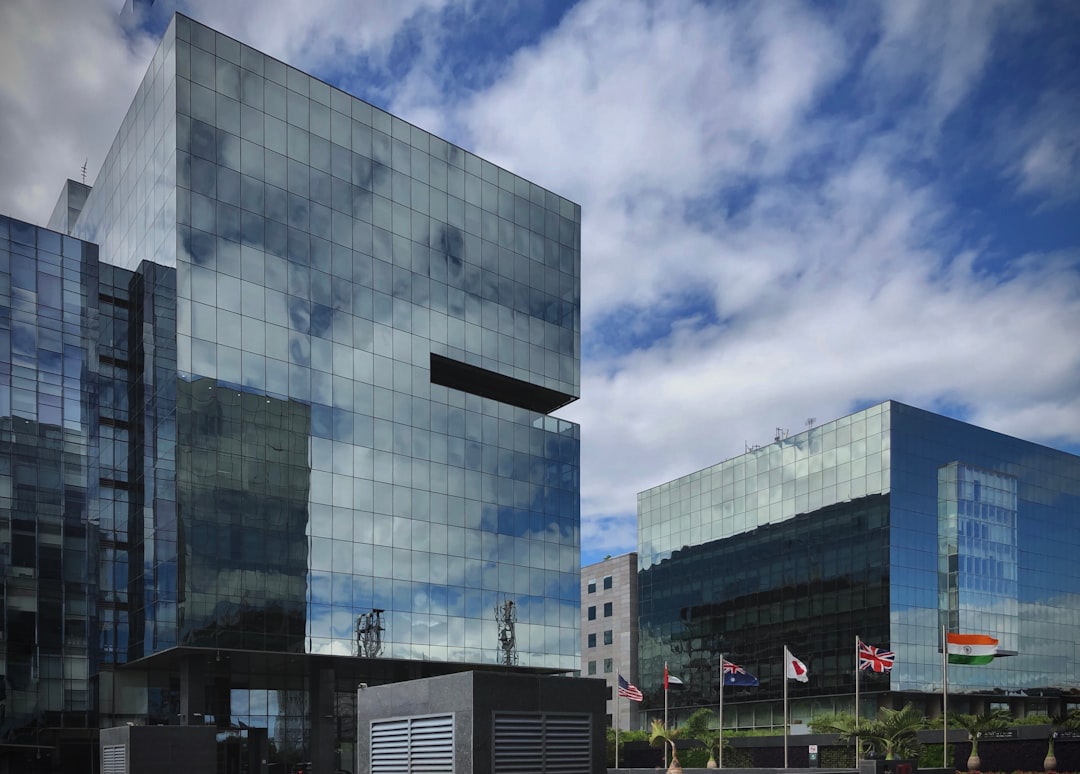
India’s REIT market demonstrated robust growth in the office sector, driven by strong leasing demand for institutional-grade office space. This demand is not theoretical: it shows up directly in occupancy numbers.
All 3 office REITs in India achieved occupancy rates close to 90% at the end of Q1 2025. High occupancy means stable rental income, and stable rental income means consistent distributions for unitholders. As of October 2025, over 23 million square feet of Grade A office space was under construction.
India hosts several REITs, including Embassy Office Parks REIT, Mindspace Business Parks REIT, and Brookfield India REIT. Most of these are concentrated in urban business hubs like Gurugram, Mumbai, Bengaluru, and Hyderabad. Each hub reflects a different demand driver: tech services, global capability centres, and financial services.
Expert perspective on REITs in India
India’s REIT market is still in its early chapters, and that is precisely where the opportunity lies. Distributions have risen consistently as occupancy stabilizes near 90% across major office portfolios. The rate environment now favors yield-seeking instruments, and REITs sit at a compelling intersection of income reliability and liquidity. The SM REIT framework extends this story further down the asset-size ladder, bringing formalized governance to a segment of the market that previously operated without regulatory oversight. Investors who understand the distribution mechanics and tax treatment today will be better positioned than those who arrive after the mainstream conversation catches up.
Industry perspective, real estate investment and capital markets professionals in India
The SM REIT shift: REITs in India go smaller
The SM REIT framework, introduced by SEBI in March 2024, allows pooling of smaller, rent-generating real estate assets with a minimum asset value of Rs 50 crore per scheme. These REITs can launch multiple schemes, each listed separately on stock exchanges, offering greater flexibility.
This move aims to broaden investor access and formalize investments in Grade B and smaller commercial real estate. It benefits small developers, boosts real estate liquidity, and opens new avenues for retail and institutional investors looking for stable income-generating investments.
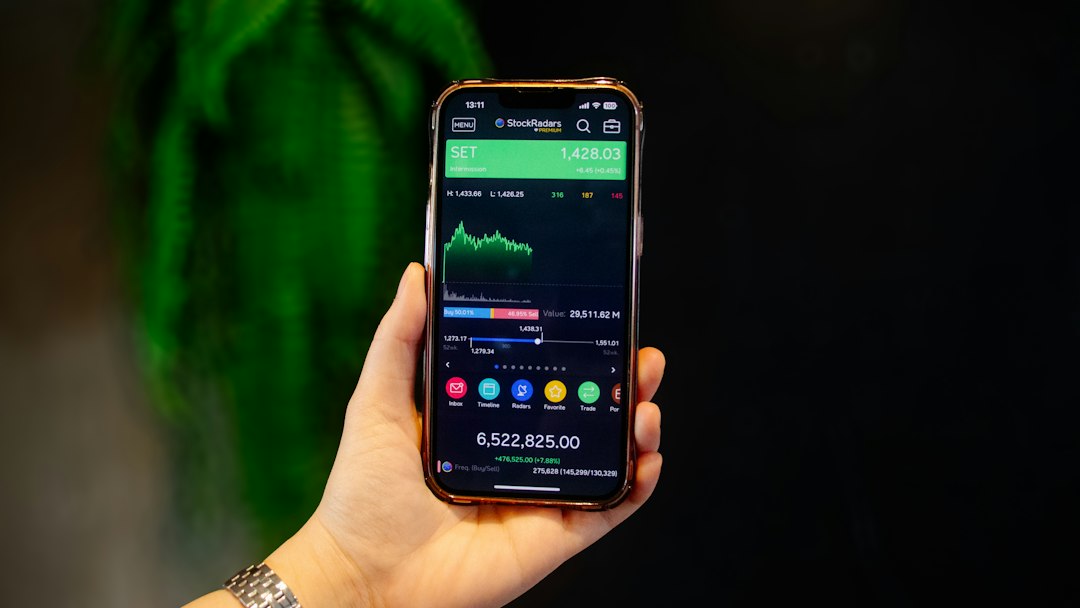
Once an SM REIT scheme is listed on the stock exchange, investors can buy units through a regular broker, just like buying shares. Platforms that previously operated as unregulated fractional ownership providers are now moving into this framework. Unlike unregulated platforms, SM REITs provide liquidity through mandatory listing requirements, addressing the critical issue of exit options for investors. The SM REIT regulatory framework balances accessibility with retail investor participation, while embedding a robust governance framework for investor protection.
Who should invest in REITs in India
REITs suit a specific investor profile, and understanding that profile saves time and prevents disappointment.
Salaried professionals who want real estate income but cannot afford a commercial property are the most natural fit. Some investors track REIT dividend stocks in India for income-generating real estate exposure, while fixed deposits offer fixed returns over a chosen tenure and usually carry lower market risk. REITs sit between those 2 poles: more return potential than a fixed deposit, more stability than pure equity.
Unlike equity dividends, REIT dividends are fully taxable at the investor’s slab rate, reducing post-tax returns for high-income investors. This is a real consideration. A person in the 30% tax bracket must factor this into yield calculations before committing capital. While REITs are more liquid than physical property, trading volumes are lower than large-cap stocks. Selling large quantities may require accepting lower prices.
Conclusion
India’s REIT market is still small, office-heavy, and under-penetrated. This looks less like the end of a rally and more like the early innings of a longer story. REITs in India now offer 5 listed options, a rising distributions track record, and a new SM REIT layer for smaller assets. The structure is clear, the regulation is strong, and the income case is real. If you are building a portfolio that generates income without requiring active management, REITs in India deserve a deliberate look. Research the listed options, compare distribution yields, check your tax position, and consult a registered investment advisor before you commit.
Discover more about REITs in India
- SEBI Real Estate Investment Trusts Regulations and Updates
- Cushman & Wakefield: India Office REITs Outperform BSE Realty Index
- Business Standard: REITs promise stable income but investors must brace for volatility