CONTACT
  • Login
  • Register
Upgrade
INDIAwebzine
Advertisement
  • Home
    • Our Authors
    • Media Kit
    • Contact
    • Cookie Policy
    • Terms and Conditions
  • News
  • Business
  • Lifestyle
    • Gastronomy
    • Sustainable living
    • Well-being
  • Culture
  • Sports
  • Travel
  • Global India
  • Insights
  • Local Guide
    • Activities in India
    • Hotels in India
    • Nightlife in India
    • Restaurants in India
    • Services in India
    • Shopping in India
  • Home
    • Our Authors
    • Media Kit
    • Contact
    • Cookie Policy
    • Terms and Conditions
  • News
  • Business
  • Lifestyle
    • Gastronomy
    • Sustainable living
    • Well-being
  • Culture
  • Sports
  • Travel
  • Global India
  • Insights
  • Local Guide
    • Activities in India
    • Hotels in India
    • Nightlife in India
    • Restaurants in India
    • Services in India
    • Shopping in India
No Result
View All Result
INDIAwebzine
No Result
View All Result
Home Business

PPF account: rules, limits and who benefits

Everything Indian investors need to know about PPF accounts, from deposit rules to who earns the most from them.

0
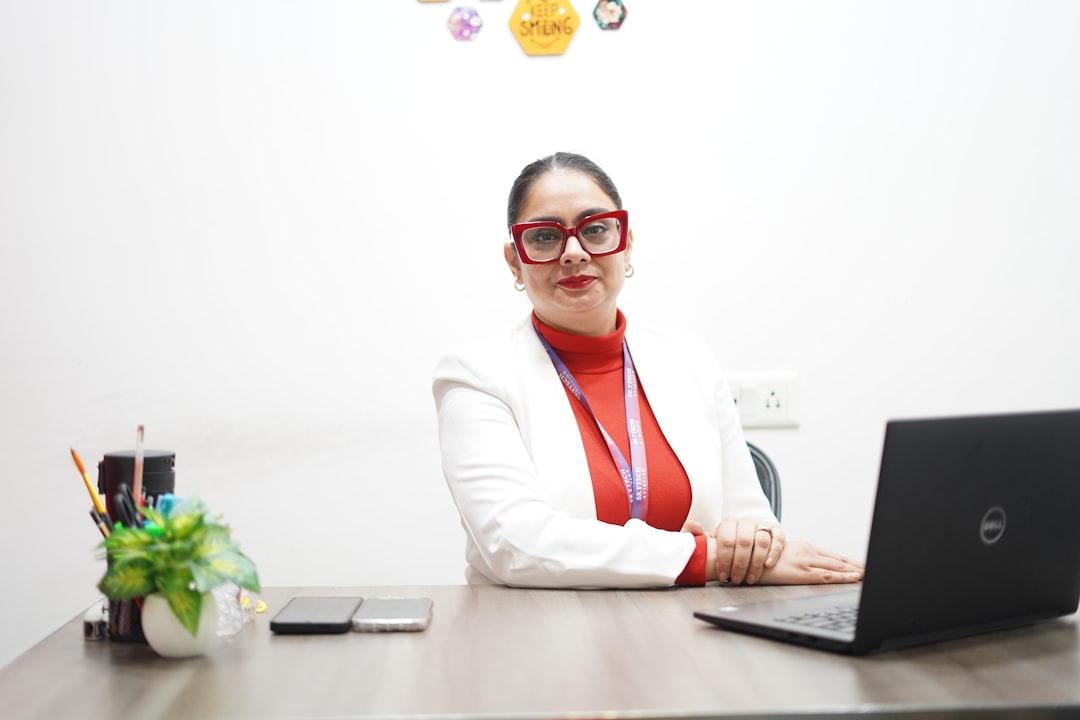
A woman in India reviews her PPF account statements at a desk, planning her long-term savings strategy.

A PPF account sits quietly in millions of Indian portfolios, yet founders and first-generation investors often overlook its full power until they calculate the tax they could have saved.

What a PPF account is and how it works

The Public Provident Fund (PPF) is one of the most widely used government-backed savings schemes in India, valued for its tax benefits, safety, and flexibility. The Public Provident Fund scheme was introduced by the Government of India in 1968 to encourage long-term savings among citizens.
Your Local Guide to India Your Local Guide to India Your Local Guide to India

A PPF account comes with a lock-in period of 15 years and allows individuals to build a substantial financial corpus through regular contributions and annual compounding. The interest rate is determined by the Government of India and revised quarterly. Currently, the PPF interest rate stands at 7.1% per annum.

You can make contributions in a lump sum or up to 12 instalments per year. Accepted modes include online transfer, cash, cheque, or demand draft. PPF interest is calculated monthly on the lowest balance between the 5th and the last day of each month. The system computes interest based on the minimum balance available before the 5th of each month.

Deposit limits and key rules

To keep your PPF account active and earning interest, you must deposit at least Rs 500 in a financial year. The maximum amount you can deposit in your PPF account, including any minor account where you are guardian, is Rs 1,50,000 in a financial year.

Any amount above Rs 1.5 lakh will not earn interest. That excess amount also will not qualify for deduction under Section 80C for that year. Depositing before the 5th of each month helps you earn interest for that full month, which adds a meaningful amount over 15 years.

Any resident Indian individual can open 1 PPF account in their own name. A parent or legal guardian can open a PPF account on behalf of a minor, supported by valid age proof. The contribution from the minor’s account still counts towards the guardian’s combined Rs 1.5 lakh limit. The PPF scheme does not allow joint account holders.
Tax benefits: why the EEE status matters

One of the key benefits of PPF is its Exempt-Exempt-Exempt (EEE) tax status. Contributions up to Rs 1.5 lakh per year qualify for deduction under Section 80C under the old tax regime; interest earned every year is completely tax-free under Section 10(11); and the entire maturity amount is also tax-exempt.

For a 30% tax bracket investor, the annual Section 80C saving alone is Rs 46,800 per year. Over 15 years, that saving compounds into a significant figure. No other fixed-income product in India combines this level of safety with full tax exemption at all 3 stages.

The PPF is backed by the Government of India, making it a low-risk option for long-term savings. Since returns are not linked to market performance, PPF suits investors looking for stable growth. The balance in a PPF account is also protected from attachment under a court order or decree, subject to applicable provisions.
A young Indian entrepreneur checks his PPF account balance on a mobile banking app to track tax savings.

Expert perspective on PPF as a wealth tool

A PPF account is not simply a tax-saving instrument for the end of the financial year. It is a disciplined, structured savings vehicle that forces wealth accumulation over a 15-year horizon. For self-employed professionals and small business founders, who have no employer provident fund, the PPF fills a critical gap in retirement planning. The government backing eliminates counterparty risk entirely. The EEE tax treatment means every rupee saved on tax is a rupee that continues to compound inside the account. Investors who treat the annual Rs 1.5 lakh ceiling as a minimum commitment, rather than a maximum, and deposit before the 5th of April each year, extract the highest possible value from this scheme.

Industry perspective, personal finance and investment advisory professionals in India

Withdrawal rules and the loan facility

A loan is available after 1 year, up to 25% of the account balance. Partial withdrawal is allowed after 5 years, and full withdrawal is available after 15 years. The loan must be repaid within 36 months, and interest is charged at 1% per annum above the applicable PPF interest rate.

In the 5-year period following an account extension with contributions, you can withdraw 60% of the balance accumulated at the time of the extension. You are limited to 1 withdrawal annually. The account holder has an option to extend the duration by a block of 5 years. There is no limit on the number of times an investor can extend their account.
-

A focused Indian professional reviews REITs in India unit statements at a modern office desk

REITs in India: how they work and pay

17/09/2026
A skilled artisan woman works on a handloom in a regional craft export workshop in India

Craft export: scale without losing handmade soul

11/09/2026
A focused Indian woman reviews her equity portfolio on a laptop before the festive season rally begins

Equity portfolio review before India’s festive rally

01/09/2026
A young Indian professional woman reviewing mutual fund SIPs on her laptop at a modern home office desk

Mutual fund SIPs: why late August wins

30/08/2026
An Indian founder at a desk reviewing revenue data, representing the discipline behind bootstrapped businesses in India

Bootstrapped businesses that crossed 10 crore

29/08/2026
A young Indian woman entrepreneur completing her trademark registration application at a desk in a modern Mumbai office

Trademark registration in India: your guide

28/08/2026

If a person opened a PPF account while they were a resident and later became an NRI, the account can run until original maturity but cannot be extended beyond 15 years. Hindu Undivided Families (HUFs) cannot open new PPF accounts.
An Indian family sits with a financial advisor to discuss opening a PPF account for their child's future.

Who benefits most from a PPF account

The PPF account delivers the most value to 3 clear groups. First, salaried workers in the 20% to 30% tax bracket gain the most from the Section 80C deduction combined with tax-free interest. Second, self-employed professionals and founders who have no access to employer provident fund schemes benefit from the retirement corpus the PPF builds over time. Third, conservative first-generation investors who cannot afford market risk get guaranteed, government-backed growth.

What makes the PPF particularly relevant today is its position as the foundation of risk-free wealth for every Indian, regardless of income level or investment experience. For the first-generation investor from a small town, it offers a structured, disciplined savings path. For the senior executive managing a complex portfolio, it provides the guaranteed, tax-free fixed-income anchor that no other instrument can match.

Parents also benefit strongly. Opening a PPF account for a child at birth means the account matures by the time the child reaches 15, creating a tax-free education or career fund with zero market exposure.
Conclusion

A PPF account is one of the most consistent and reliable savings tools available to Indian investors. The combination of government-backed safety, a 7.1% annual interest rate, and full EEE tax exemption makes the PPF account worth prioritising before exploring higher-risk options. Whether you are a salaried professional, a startup founder, or a parent planning for a child’s future, this scheme rewards discipline and patience over 15 years. Open your PPF account today, deposit before the 5th of April, and let the compounding begin.

Discover more about PPF account

  • Public Provident Fund (PPF): Interest Rate, Tax Benefits and Withdrawal Rules
  • PPF (Public Provident Fund): Eligibility, Tax Benefits and Interest Rate
  • PPF Account India 2026: Interest Rates and Tax Benefits
author avatar
Ananya Krishnan
Ananya Krishnan grew up in Jaipur and has spent the last decade writing about India's vibrant lifestyle scene. From Ayurvedic wellness traditions to contemporary street fashion in Mumbai's emerging neighbourhoods, she covers Indian life with warmth and cultural pride. She is passionate about showing the world that modern India and ancient tradition can coexist beautifully.
See Full Bio
Previous Post

Raksha Bandhan gifting reshaped by D2C brands

Next Post

Monsoon wellness habits Ayurveda recommends

Related Posts

A focused Indian professional reviews REITs in India unit statements at a modern office desk
Business

REITs in India: how they work and pay

17/09/2026
A skilled artisan woman works on a handloom in a regional craft export workshop in India
Business

Craft export: scale without losing handmade soul

11/09/2026
A focused Indian woman reviews her equity portfolio on a laptop before the festive season rally begins
Business

Equity portfolio review before India’s festive rally

01/09/2026
A young Indian professional woman reviewing mutual fund SIPs on her laptop at a modern home office desk
Business

Mutual fund SIPs: why late August wins

30/08/2026
An Indian founder at a desk reviewing revenue data, representing the discipline behind bootstrapped businesses in India
Business

Bootstrapped businesses that crossed 10 crore

29/08/2026
Next Post
A woman practicing monsoon wellness by drinking warm tulsi ginger tea at home in India

Monsoon wellness habits Ayurveda recommends

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Truelang AI WordPress Translation Plugin Truelang AI WordPress Translation Plugin Truelang AI WordPress Translation Plugin
No Result
View All Result

Our Focus

INDIAwebzine is your international window on India: sustainable lifestyle, business, culture, sports and events for a global audience drawn to the subcontinent's vibrant and diverse scene.

Our Readers

INDIAwebzine addresses readers who engage with India at a high level: professionally, financially, strategically, and as decision-makers in their fields.

Our Approach

Lifestyle, travel, and culture are integrated as context and indicators of economic dynamism, purchasing power, and soft power — not standalone entertainment.

Recent Posts

  • Block printing at home with Indian stamps
  • Festive reset: home and wardrobe in India

© 2025 INDIAwebzine by NOOR & NOOR.

Welcome Back!

Login to your account below

Forgotten Password? Sign Up

Create New Account!

Fill the forms bellow to register

All fields are required. Log In

Retrieve your password

Please enter your username or email address to reset your password.

Log In
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}
No Result
View All Result
  • Home
    • Our Authors
    • Media Kit
    • Contact
    • Cookie Policy
    • Terms and Conditions
  • News
  • Business
  • Lifestyle
    • Gastronomy
    • Sustainable living
    • Well-being
  • Culture
  • Sports
  • Travel
  • Global India
  • Insights
  • Local Guide
    • Activities in India
    • Hotels in India
    • Nightlife in India
    • Restaurants in India
    • Services in India
    • Shopping in India

© 2025 INDIAwebzine by NOOR & NOOR.

Verified by MonsterInsights
enEnglishhiहिन्दी